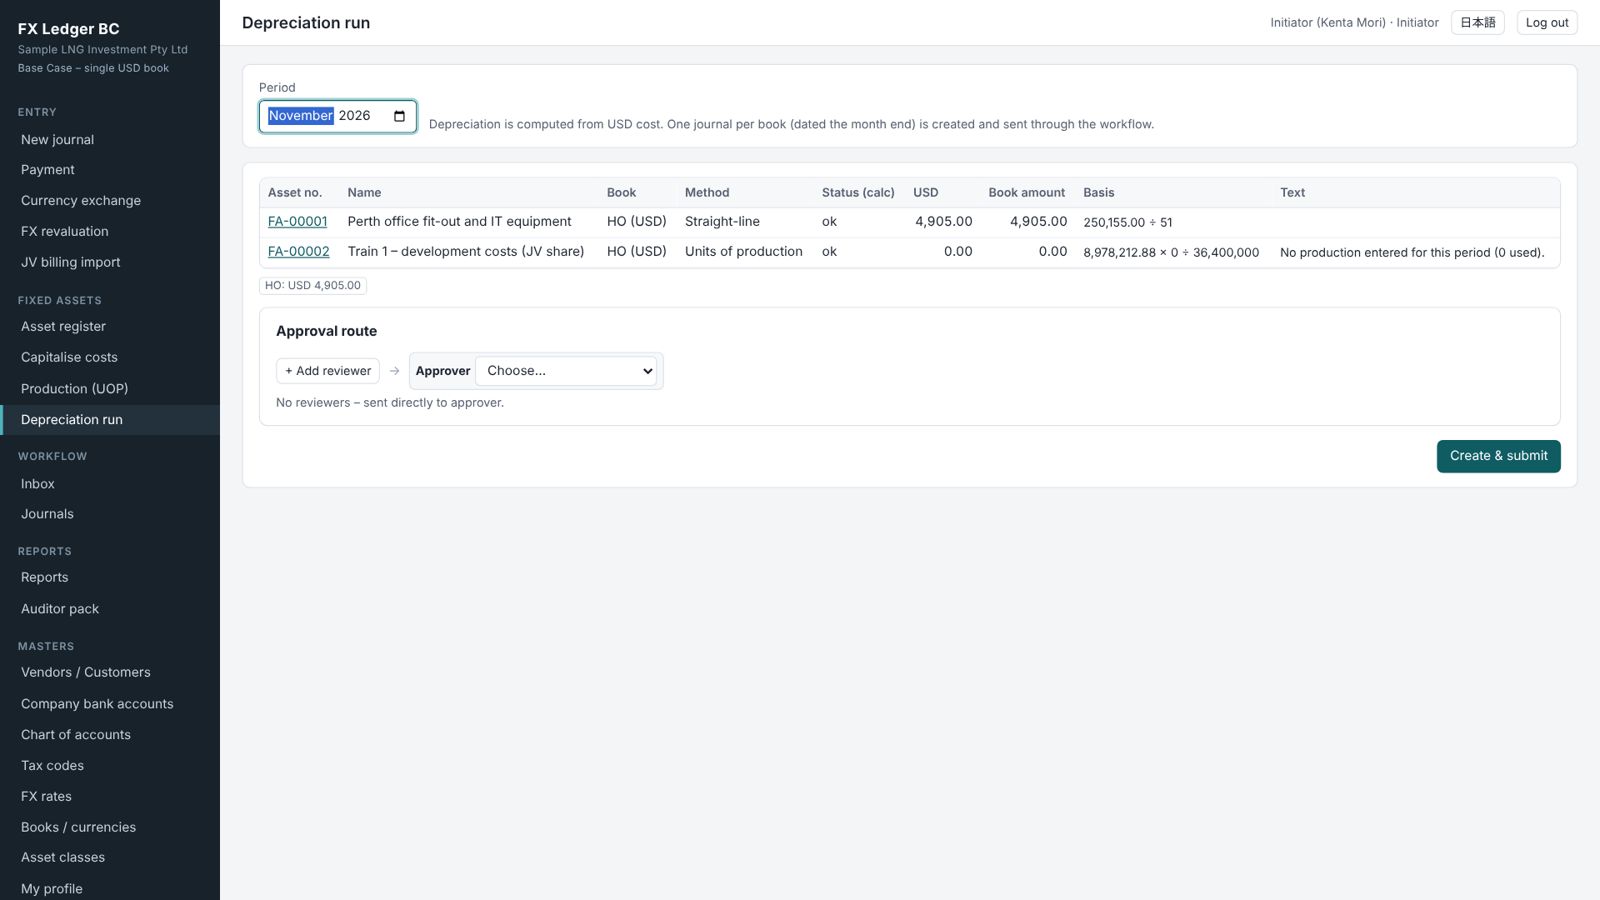
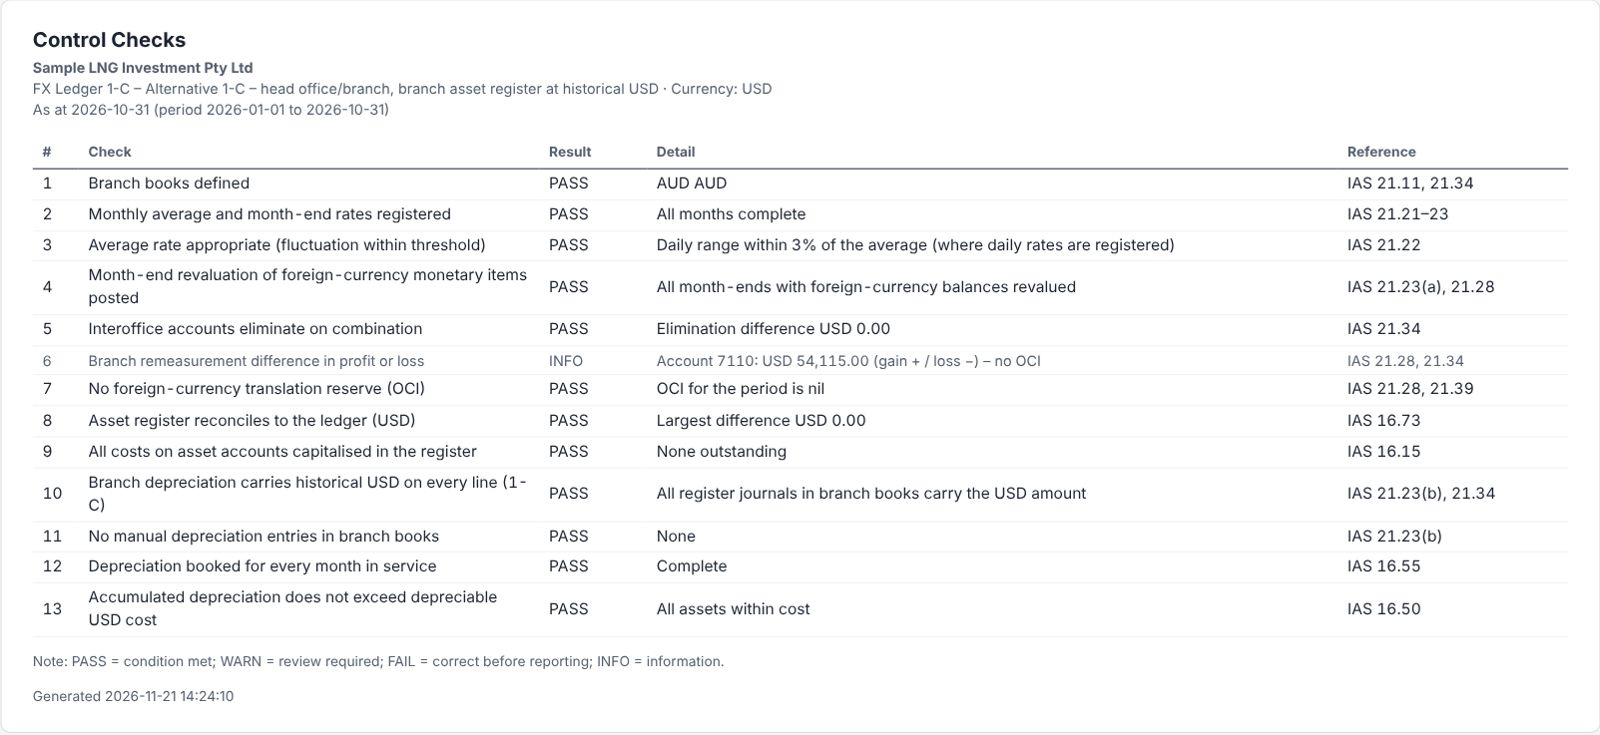
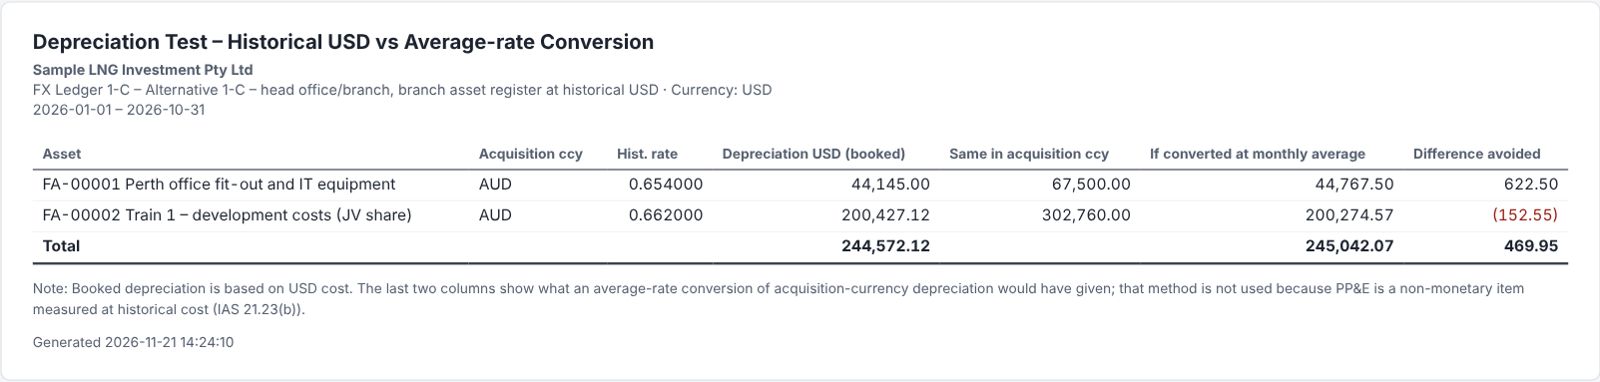
How should an Australian entity with USD functional currency record AUD CAPEX and depreciation under IFRS? We publish the discussion paper and three accounting web apps, one for each bookkeeping method studied (Base Case, 1-C, 1-D). Each includes a fixed asset register (straight-line and units of production) and generates an auditor pack that explains the translation to the accountant.

"Bookkeeping Alternatives for Foreign-Currency CAPEX and Depreciation" (Japanese and English, A4, about 10 pages). It sets out IFRS correctness and practical burden under IAS 21 for discussion with the accountant.
USD is the functional currency. Foreign-currency CAPEX is fixed at USD cost on the payment date and not retranslated; depreciation is computed from USD cost. The AUD branch is remeasured (IAS 21.34), not translated.
Steps, journals and remeasurement worksheets for the Base Case, 1-C, 1-D and method 2, with a numerical example showing identical statements.
The Base Case is recommended; 1-C and 1-D are acceptable with conditions; method 2 is not recommended (fictitious FX, effectively two ledgers, heavy audit work).
Transaction and USD amounts on each line, a monetary flag per account, a rate table and a register holding USD cost form the common core.
Eight items including the status of the branch, use of average rates, CAPEX thresholds and the nature of JV cash calls (IFRIC 22).
| Method | Depreciation | FX (P/L) | Net loss | OCI | PP&E NBV | Verdict |
|---|---|---|---|---|---|---|
| Base / 1-C / 1-D / 2 (correct remeasurement) | 130,000 | +17,000 | 385,000 | 0 | 520,000 | ✓ |
| Depreciation at average rate (mixed) | 136,000 | +17,000 | 391,000 | 0 | 514,000 | ✗ |
| Branch translated as a foreign operation | 136,000 | 0 | 408,000 | +63,000 | 560,000 | ✗ |
| Method 2, simple translation | 136,000 | −76,593 | 484,593 | +139,593 | 560,000 | ✗ |
Both language versions of the paper are in Downloads.
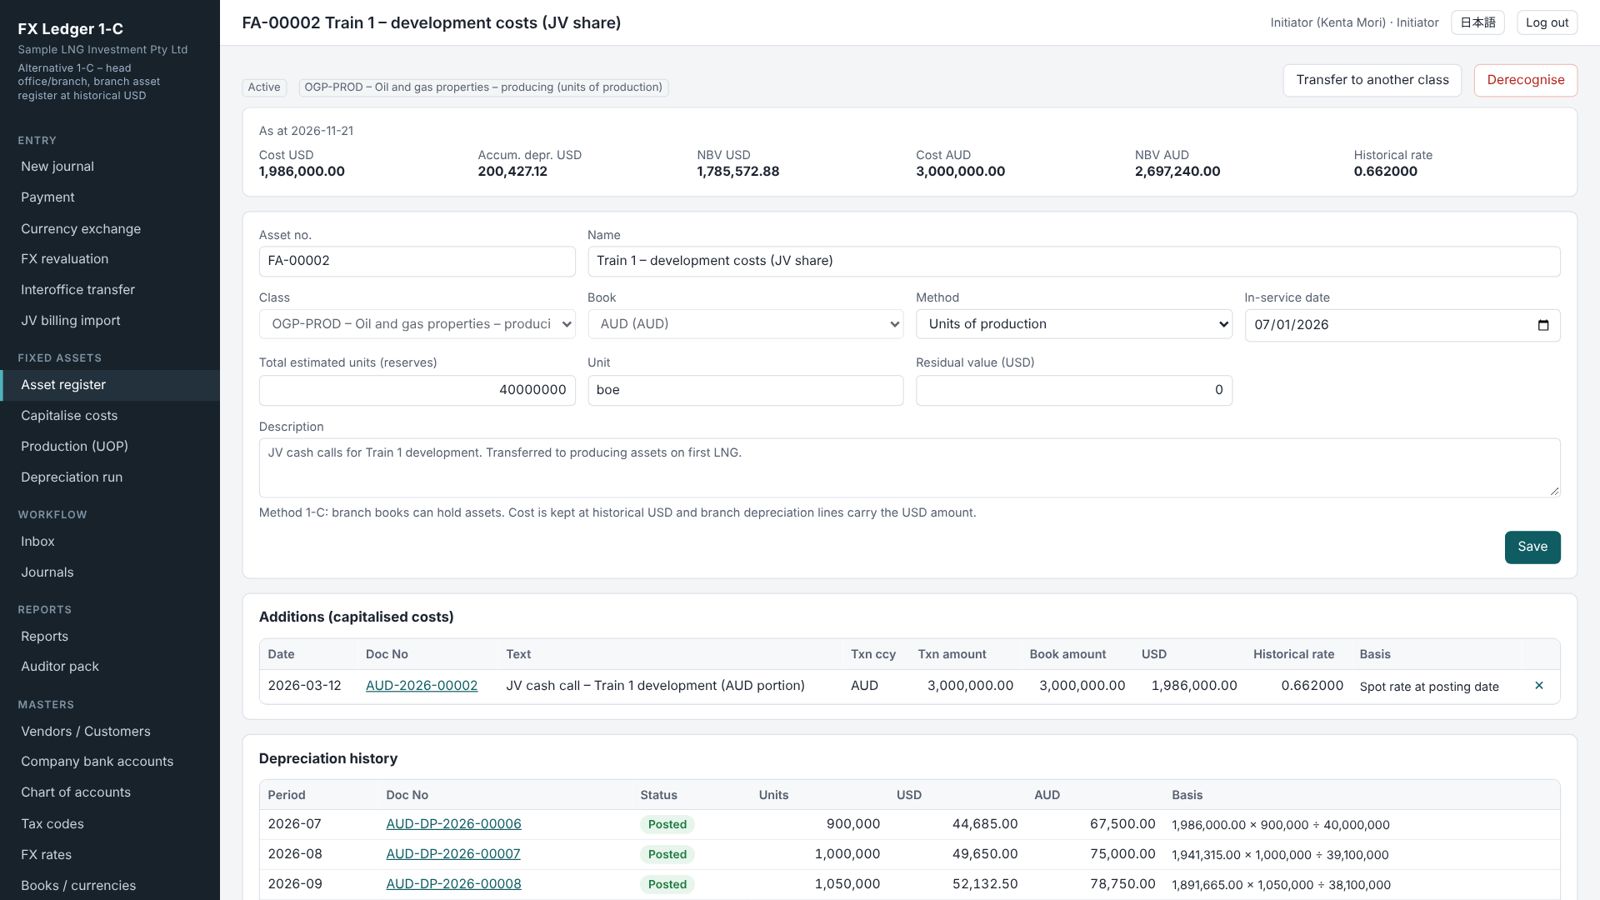
Built on FX Ledger (head office/branch) and JVLedger (single USD book), each method is a separate system. All three hold the same sample transactions (Jan–Oct 2026) and give identical statements.
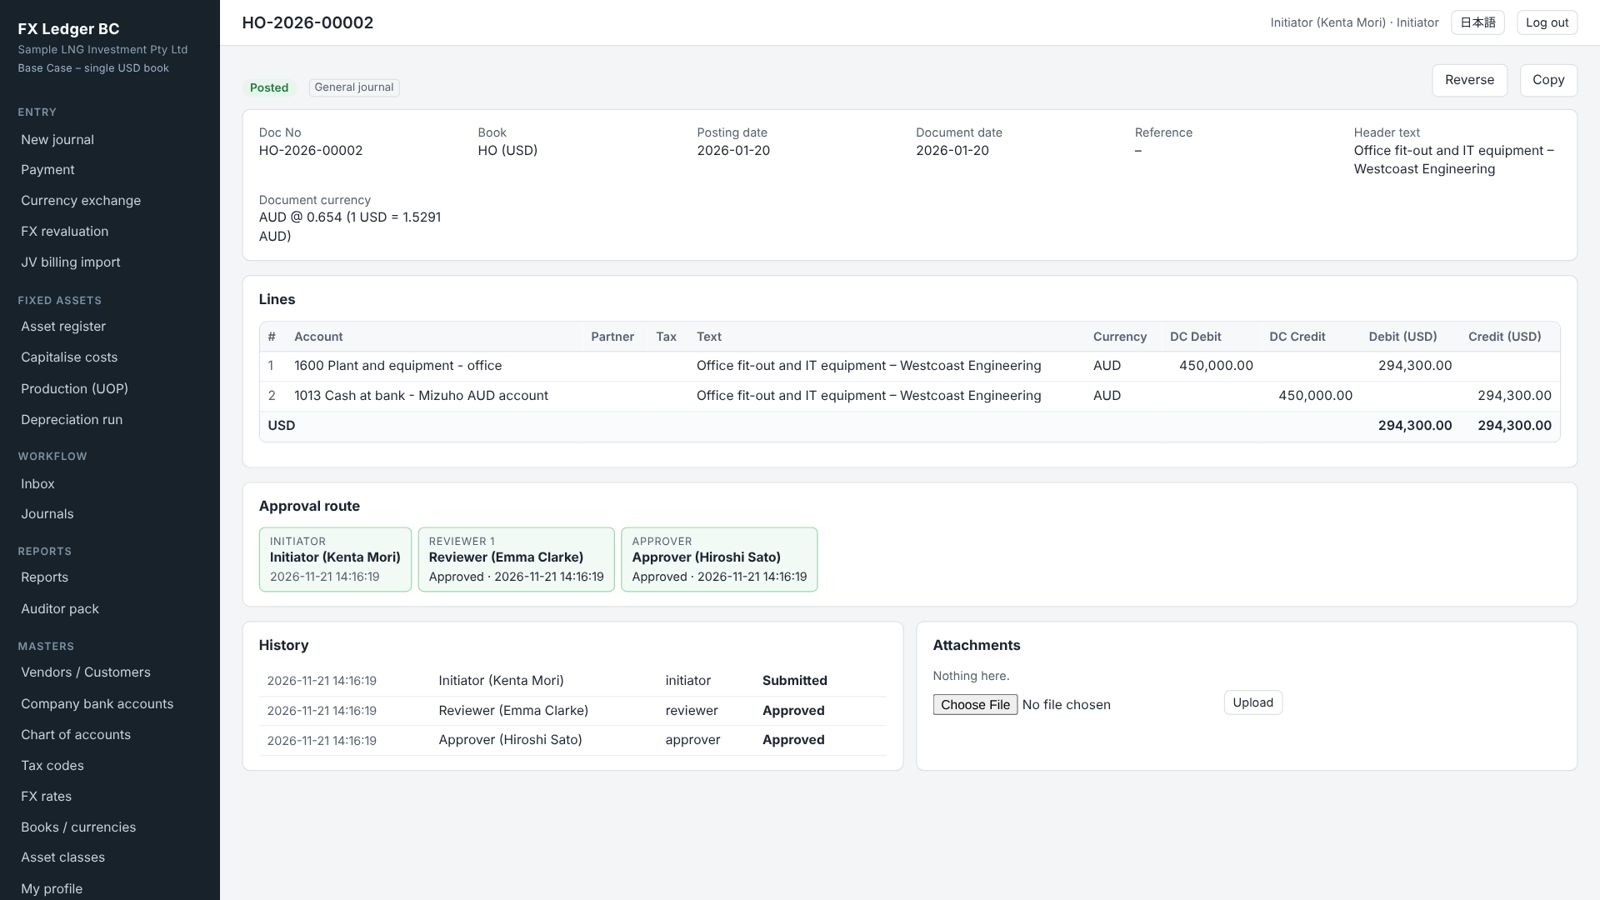
One USD book. AUD and other currencies are recorded as foreign-currency transactions at the transaction-date rate, keeping the transaction amount.

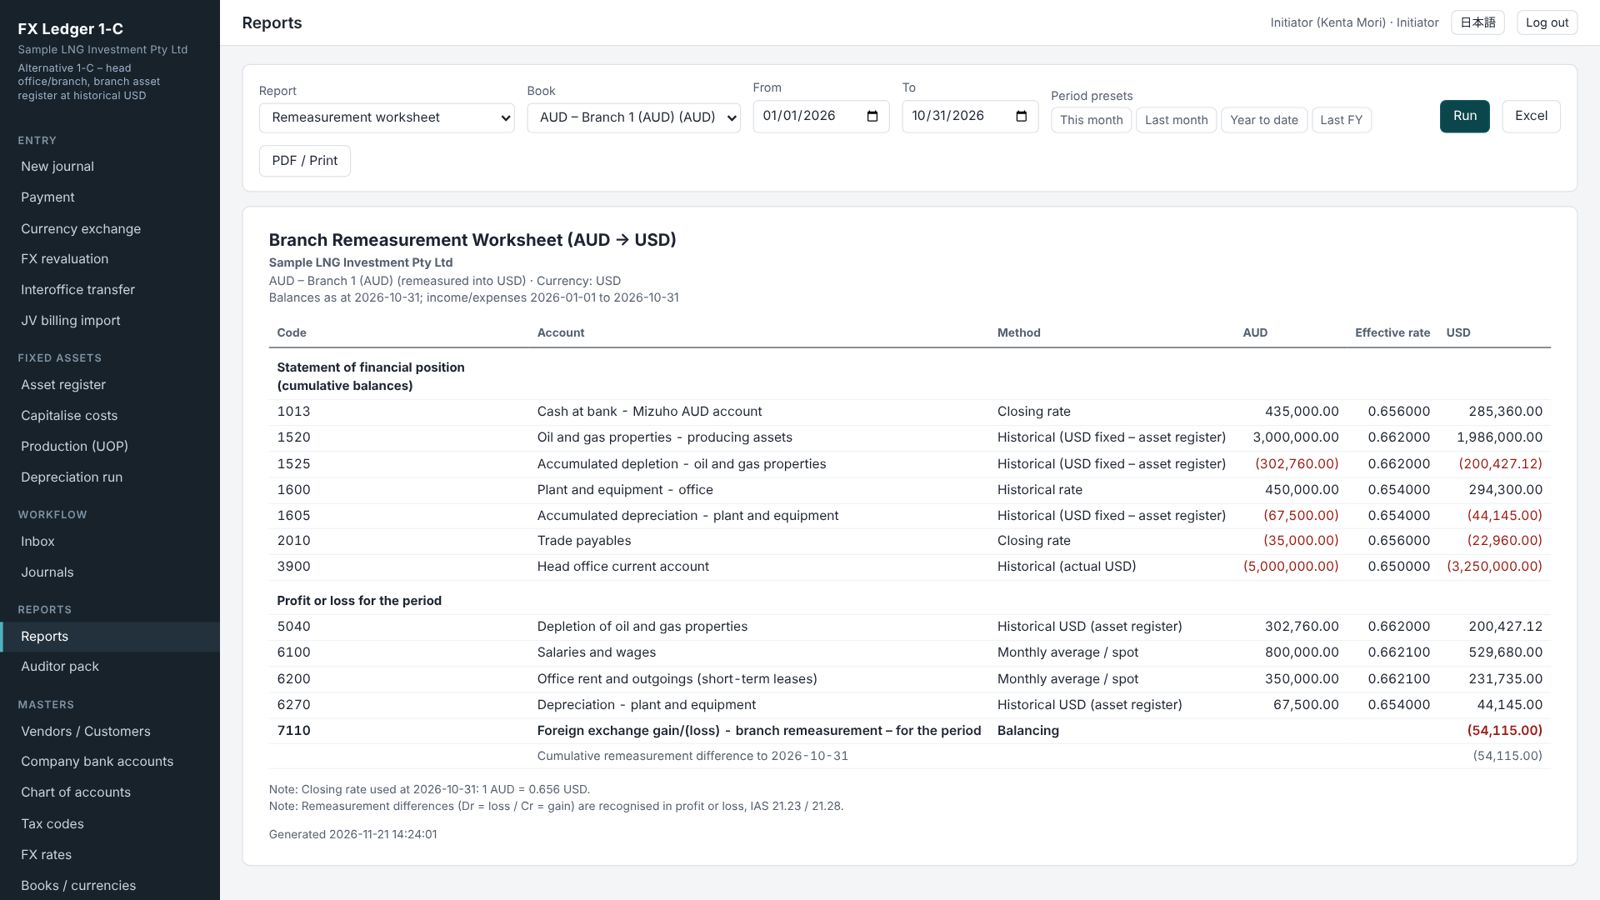
USD head office and AUD branch, remeasured under IAS 21.34. Branch assets keep historical USD in the register.

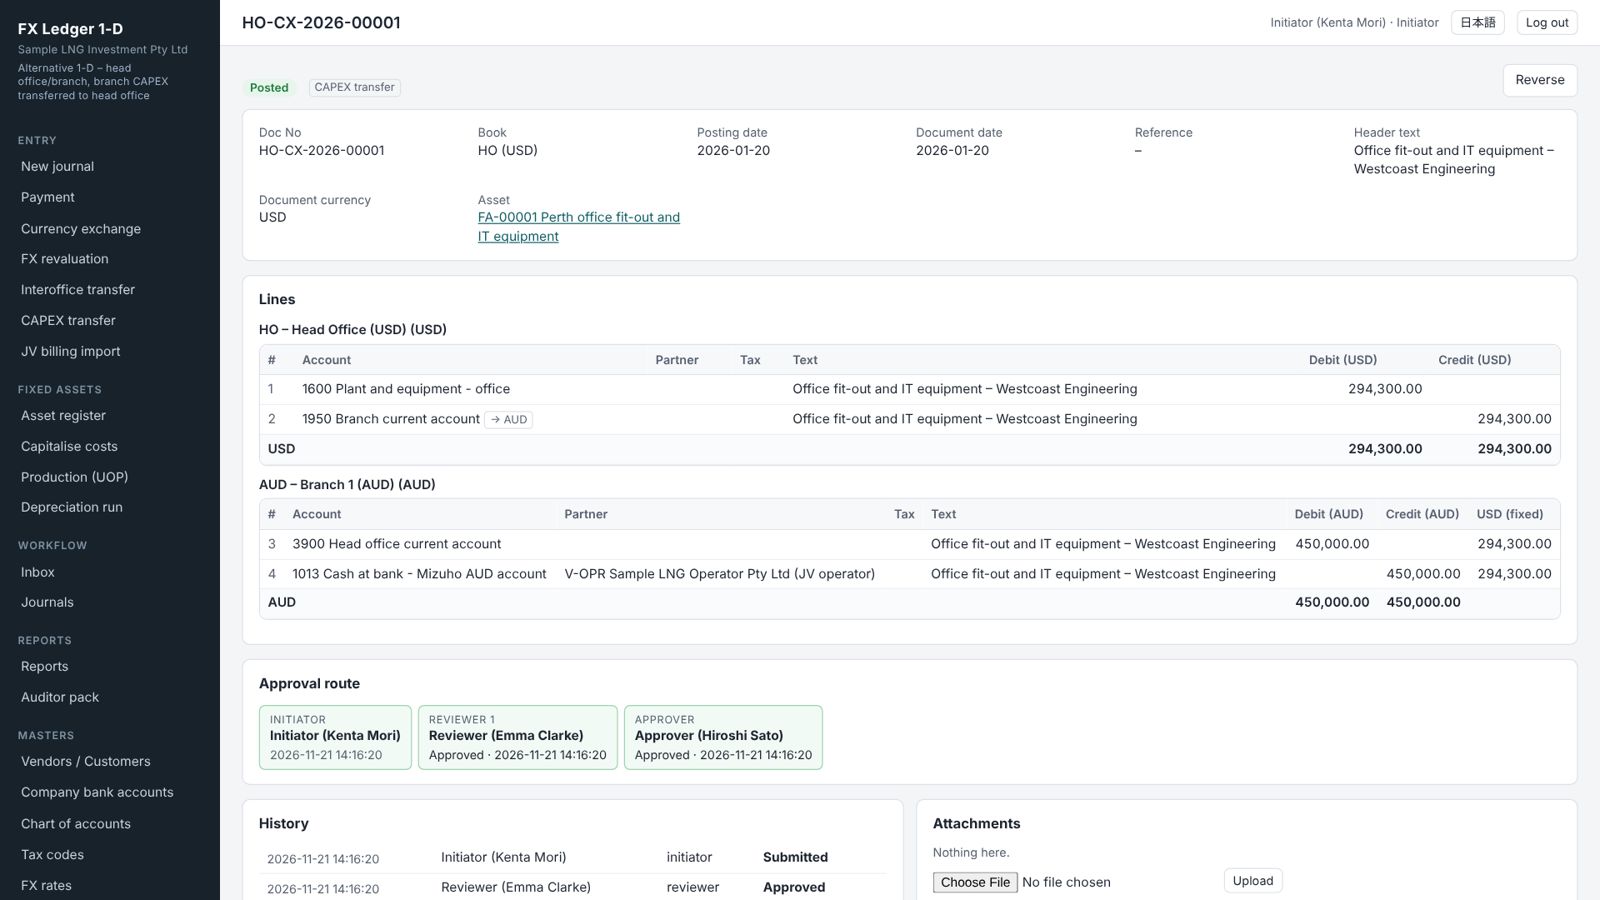
USD head office and AUD branch. CAPEX paid by the branch is transferred to a head office USD asset with a “CAPEX transfer”.

| FX Ledger BC | FX Ledger 1-C | FX Ledger 1-D | |
|---|---|---|---|
| Net loss | 1,909,232.12 | 1,909,232.12 | 1,909,232.12 |
| Total assets (31 Oct) | 18,113,727.88 | 18,113,727.88 | 18,113,727.88 |
| OCI | 0 | 0 | 0 |
| Register vs ledger difference | 0.00 | 0.00 | 0.00 |
Journals with transaction currency and rate; USD computed automatically.
Foreign-currency cash and payables at the closing rate, reversed on the 1st.
ABA, ISO 20022 pain.001, CSV – created at final approval.
Financial position, comprehensive income, equity, cash flows (indirect).
Draft journals from the Excel billing statement (IFRS 11).
Initiator → reviewers (0–5) → approver, with segregation of duties.
No posting into locked periods; every action logged.
Screen language per user; reports in English.
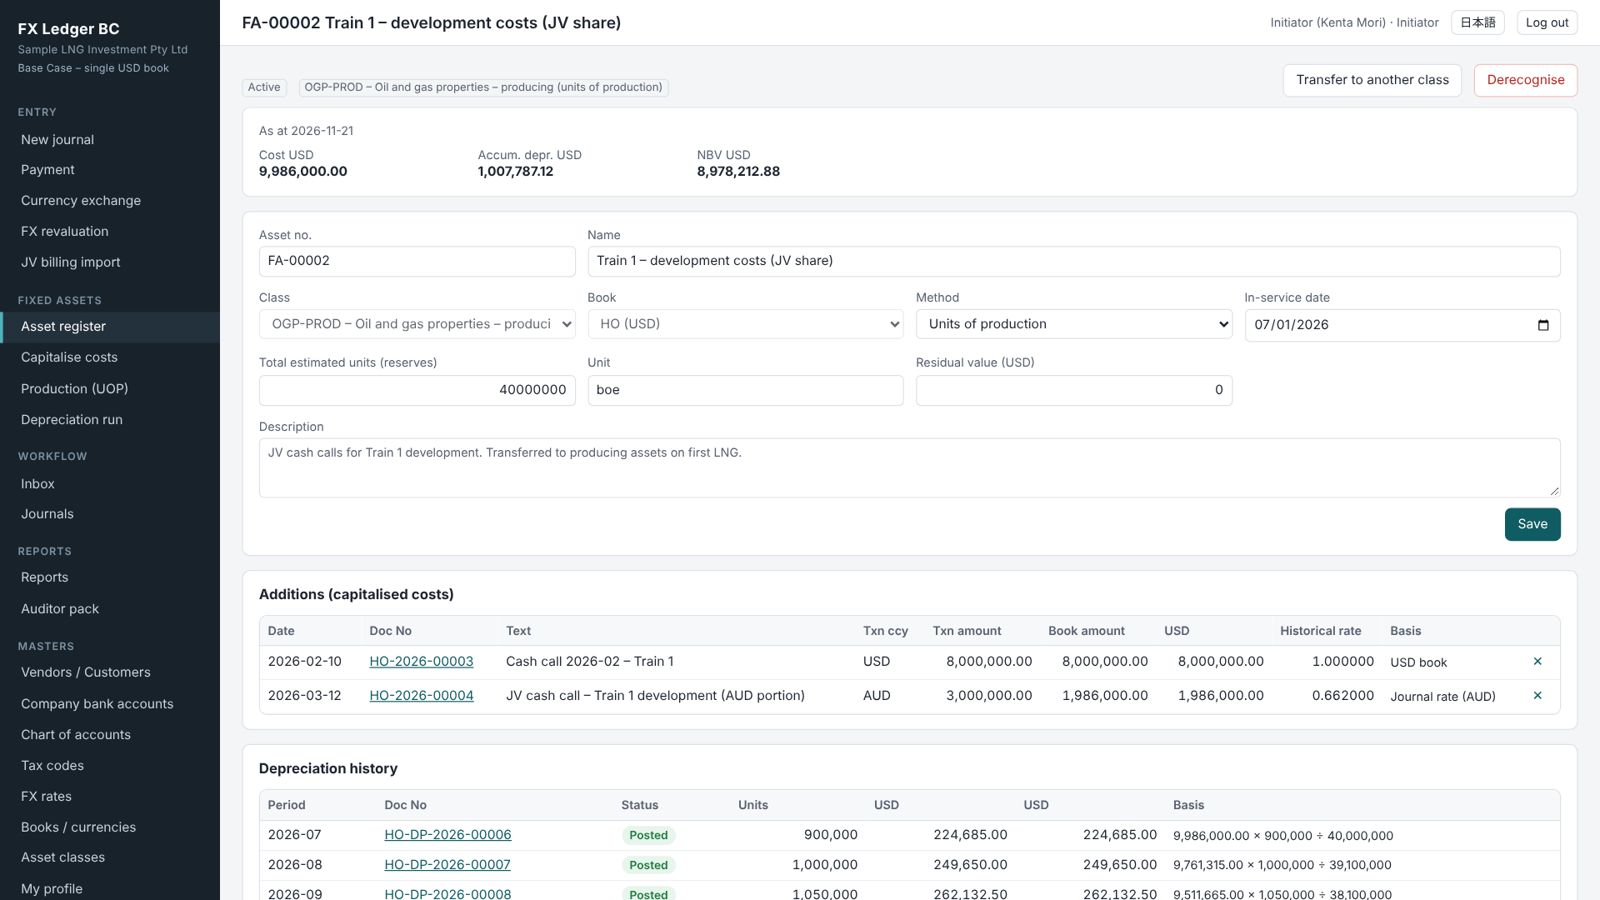
Cost is fixed in USD and depreciation is always computed from USD cost (IAS 21.23(b), IAS 16.50).


Choose the period and language (Japanese / English) to generate the pack explaining the translation. Output on screen, to Excel (one sheet per section) or to PDF.


The same accounts work in all three apps. Enter journals or a depreciation run as the initiator, then log in as the reviewer and the approver to follow the flow to posting.
| Role | Username (ID) | Password | What to try |
|---|---|---|---|
| 1. System Admin | admin | adminashikari | Users, rates, asset classes, settings (rate source, average-rate threshold), audit log, all reports |
| 2. Initiator | init01 | Testinitiator1 | Foreign-currency journals, currency exchange, CAPEX transfer (1-D), asset registration, production, depreciation run, revaluation, auditor pack |
| 3. Reviewer | rev01 | Testreviewer1 | Review, approve, return or reject |
| 4. Approver | appr01 | Testapprover1 | Final approval (posting), payment file output |
The key points of the paper and the fixed asset, CAPEX transfer and auditor pack functions of the three apps, shown with sample-data screens and captions (no narration).
Comparison of bookkeeping methods: situation, IFRS treatment, procedures, pros and cons, system design points, questions for the accountant.
Download1920×1080 with burned-in captions. The SRT file is also available.
Download MP4 Captions (SRT)| Server | PHP 8.1+, MySQL 5.7+ / MariaDB 10.3+ (standard cPanel hosting) |
|---|---|
| Method | Chosen in config.php at installation (BC / 1C / 1D); cannot be changed later |
| Banks | Mizuho and MUFG Sydney branches (USD and AUD accounts) |
| Security | HTTPS, hashed passwords, lockout after failed logins, CSRF protection, audit log |
| Not included | Impairment (IAS 36), revaluation model, partial disposals, automatic production import, bank API integration |
The paper and the apps are material for discussion with the accountant and do not replace professional accounting, audit or tax advice.